The Rise of Platform-Based Professional Services
Professional services have traditionally operated through fragmented systems. Accounting firms, corporate service providers, tax advisors, and auditors often function as separate entities with their own processes, communication channels, and document management practices.
For businesses operating across multiple jurisdictions or regulatory environments, this fragmentation can create complexity. Information may be shared through emails, spreadsheets, and scattered document repositories, making coordination between service providers slow and difficult to track.
In recent years, this structure has begun to change. Increasingly, professional services are being delivered through integrated digital platforms that centralise communication, documentation, compliance processes, and financial reporting.
This shift reflects a broader transformation in how businesses manage operational infrastructure.
Fragmentation in Traditional Professional Services
Historically, professional services developed as specialised disciplines.
Accounting firms focused on financial reporting and bookkeeping. Corporate service providers handled company formation and regulatory filings. Tax advisors concentrated on planning and compliance, while auditors maintained independent oversight of financial statements.
While this specialisation provides technical expertise, it often creates operational fragmentation. Businesses may interact with multiple advisors who rely on different systems and processes. Documents are requested repeatedly, deadlines are tracked across separate channels, and communication may occur through informal exchanges.
These fragmented structures can create inefficiencies and increase the risk of information gaps.
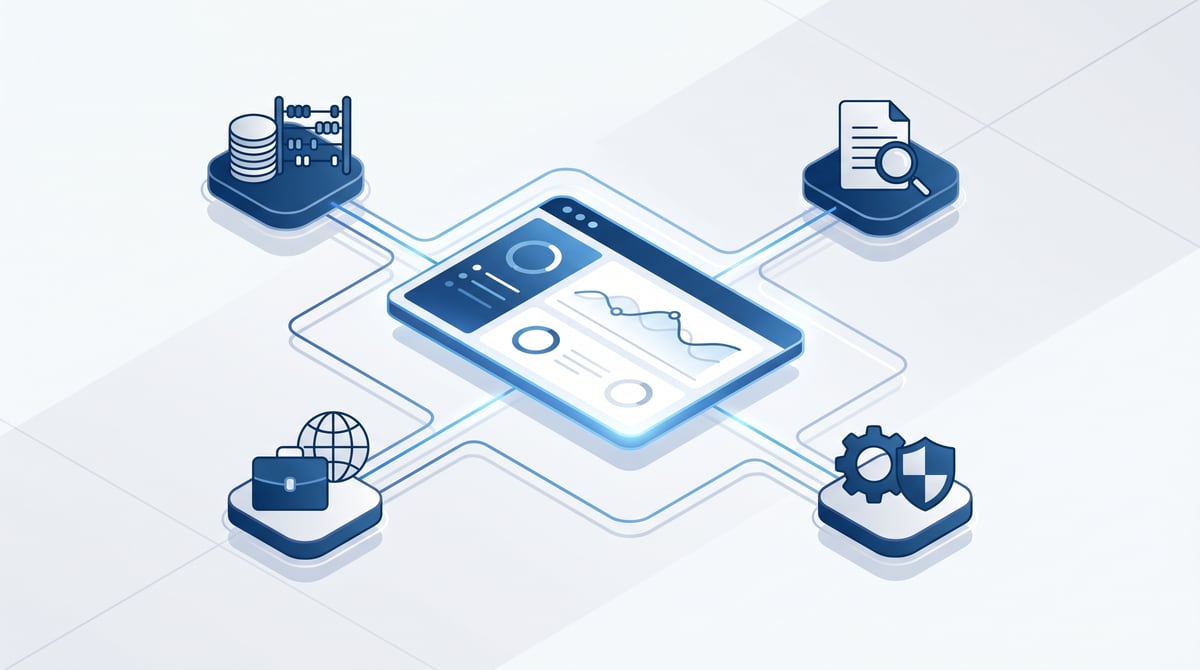
The table below contrasts the traditional fragmented model with the platform-based approach.
| Aspect | Fragmented professional services | Platform-based professional services |
|---|---|---|
| Service delivery | Separate advisors and systems | Unified digital environment |
| Documents | Requested repeatedly across channels | Uploaded once, shared centrally |
| Deadlines and tasks | Tracked across separate channels | Tracked transparently in one place |
| Data flow | Manual exchange between functions | Direct flow between processes |
| Visibility | Limited and reactive | Continuous and structured |
This integrated model underpins modern accounting and advisory services.
In complex regulatory environments, coordination between advisors becomes particularly important. Without structured systems connecting these services, businesses often carry the burden of managing information flows themselves.
Digital Platforms as Operational Infrastructure
The emergence of digital platforms has begun to address these challenges.
Platform-based professional services bring multiple functions into a unified digital environment. Accounting processes, compliance tasks, document management, and client communication can operate within a single system rather than across disconnected tools.
This structure creates a centralised workspace where both service providers and clients can access relevant information. Documents are uploaded once, tasks can be tracked transparently, and financial data can flow directly between systems.
Digital platforms also allow service providers to standardise processes and reduce administrative friction. Automated workflows can manage recurring tasks such as document requests, compliance reminders, and reporting deadlines.
The result is a more structured environment for managing professional services.
The Role of Digital Transformation in Professional Services
The rise of platform-based services is closely linked to broader digital transformation trends across the economy.
The European Commission has emphasised that digital technologies are becoming essential for improving efficiency, transparency, and competitiveness within small and medium-sized enterprises (European Commission, 2023). As businesses adopt digital tools across their operations, expectations around professional services evolve accordingly.
Clients increasingly expect structured digital environments where information can be accessed easily and processes are transparent.
At the same time, regulatory systems are becoming more digital. Tax administrations, corporate registries, and financial authorities are progressively adopting electronic filing systems and digital reporting frameworks.
The OECD has highlighted how tax administrations are moving toward more integrated digital ecosystems in which financial data can be exchanged securely between businesses, service providers, and authorities (OECD, 2020).
These developments naturally support the emergence of platform-based professional services.
Integration Across Accounting, Corporate, and Compliance Functions
One of the most important advantages of digital platforms is the ability to integrate different professional services within a single operational structure.
Accounting records, corporate filings, tax compliance, and audit documentation often rely on overlapping datasets. When these functions are managed through disconnected systems, duplication of work is common.
Integrated platforms reduce this duplication by allowing information to flow directly between processes. Financial records can support tax calculations, compliance documentation can be linked to corporate records, and audit services can access structured financial data more efficiently.
This integrated approach also improves transparency. Businesses gain visibility over deadlines, requests, and ongoing work rather than relying on fragmented communication.
For companies operating internationally, this visibility becomes particularly valuable.
From Advisors to Infrastructure Providers
The evolution of platform-based professional services also reflects a broader shift in the role of service providers.
Professional firms are increasingly moving beyond traditional advisory roles toward providing operational infrastructure. Instead of simply delivering services upon request, they offer systems that support the continuous management of financial and regulatory processes.
This transformation changes how businesses interact with professional advisors. Rather than exchanging documents through periodic communication, clients operate within a shared digital environment where information, tasks, and reporting are structured from the beginning.
Such platforms allow businesses to maintain a clearer overview of their financial operations while ensuring that compliance requirements are managed systematically.
Conclusion
Professional services are undergoing a structural transformation.
The traditional model of fragmented advisors and disconnected processes is gradually giving way to integrated digital platforms that centralise financial operations, compliance management, and client communication.
This shift reflects broader changes in how businesses operate. As financial systems, regulatory reporting, and operational infrastructure become more digital, professional services must adapt to provide the same level of structure and visibility.
Platform-based service delivery offers a model in which expertise, technology, and operational systems work together.
For businesses navigating increasingly complex regulatory environments, such platforms are becoming an essential component of modern financial management. To understand where your own processes would benefit from this structure, an accounting health check is a useful starting point.
References (Official Sources)
European Commission. Digital Transformation of SMEs.
https://commission.europa.eu/projects/digital-transformation-smes_en
Organisation for Economic Co-operation and Development. Tax Administration 3.0: The Digital Transformation of Tax Administration.
European Commission. Shaping Europe’s Digital Future.